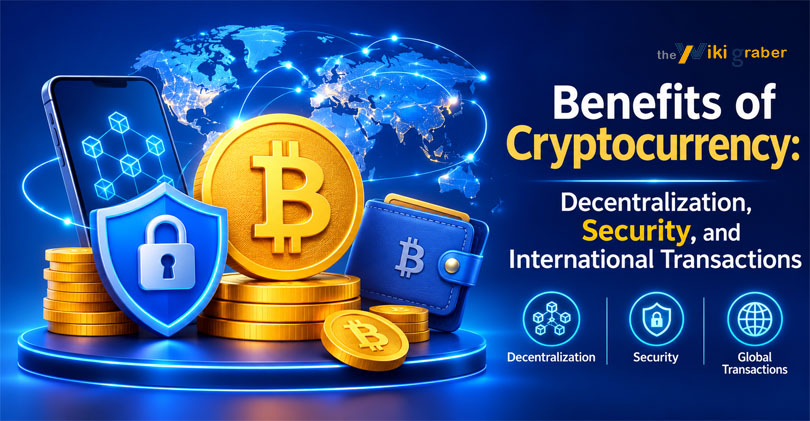

There are several key benefits to cryptocurrencies. From decentralization to low transaction costs, transparency and fast international transfers, this is what has led to the success of crypto and what has drawn users, investors and developers globally to use digital assets. However, there are not always positive aspects.
Table of Contents
Decentralization & Financial Freedom: How Cryptocurrency Removes Middlemen and Gives Individuals Greater Control Over Their Money
At its core, the idea of cryptocurrency is decentralization. So when a user makes a transaction, there is no single bank, payment provider or government approving and recording the transaction – instead it is a decentralised computer network (known as a blockchain). This means that no single institution can own the entire network or alter the history of a transaction.
This can lead to increased financial freedom for individuals. By having a smartphone and internet connection you can create a crypto wallet, receive payments and send value to anyone around the world without needing permission from a bank. Decentralised solutions can be very useful for those that are under-banked, or live in areas with unreliable banking infrastructure or want to take a different approach.
You will have full control over your private keys when using self-custody wallets. Whilst this means that you will never have to wait for banks to open or payment providers to approve a transaction, you will be responsible for losing your recovery phrase or private keys.
Whilst decentralization does not mean that you are free from inflation within crypto, you do not have to worry about holding onto your coins with various opinions from exchanges, developers, miners, validators, regulators and whales. It helps you to diversify away from a single service provider.
How Cryptocurrency Offers a Cost-Effective Alternative to Traditional Banking and International Remittances
A benefit of using crypto-coins is that you can save on transaction costs. Usually when making international payments you need to go via multiple banks, correspondent banks, currency conversion and payment providers which all incur additional charges. This can take a few days to process.
Using crypto can mean you often save on most third parties. They can send Bitcoin, stable coins and other crypto assets directly to one another. Transactions are confirmed and recorded on the blockchain network between the two wallet addresses. Transaction costs can be much less than using a wire or remittance transfer for smaller amounts.
However, this depends on what blockchain you are using, how busy the network is, size of transaction and the type of asset transferring. Some of the most popular blockchains can be very expensive to send transactions on during busy periods. Newer blockchains, layer-2s and stable coin transfers can be cheaper to use. Always check the transaction costs.
If the migrant worker can use the crypto/ stable coins they can save a lot. However they need to consider any conversion costs plus cash out costs.
How Blockchain Technology Secures Cryptocurrency Transactions and Provides Trust
Blockchain networks are secured using cryptography, decentralised ledger and consensus rules. Transactions are signed with cryptography. Each block added to the blockchain is connected to the previous block. After confirming a transaction it would be very difficult to make any changes as you would need to alter a large portion of the network.
Blockchains are also transparent. Most transactions can be seen by everyone on public blockchains. For example who sent the transaction (wallet address), amount and time. This can help reduce hidden changes or reversal of individual transactions. It can also increase audit ability, accountability and visibility.
If the migrant worker was able to use the crypto or stablecoin they could potentially save quite a bit of money on sending cash back home. However, they would have to consider the cost of converting, cashing out locally and the fluctuation between the exchange rate and local currency.
How Blockchain Technology Protects Cryptocurrency Transactions and Builds Trust
Blockchain networks are secure thanks to cryptography, decentralised accounting and consensus rules. Every transaction is cryptographically signed and each new block is linked to the last block. Once a transaction has been confirmed, it would be extremely difficult to change as you would have to change quite a large amount of the network.
It also makes a blockchain transparent. Most transactions can be seen by anyone on public blockchains, such as what wallet address, amount and time. This can help reduce covert changes or reversal of individual transactions. It can also improve auditability, accountability and public verification.
However, this does not mean that it will be completely private. The wallet addresses are pseudonymous rather than anonymous, so whilst it won’t show your name it can often be identified using exchanges, KYC and public analysis. Always assume that anything on a blockchain will be visible.
Whilst the blockchain itself may be secure, your exchange, browser extension, phone and recovery phrase can be vulnerable. Strong security should be used on your wallet, unique passwords, 2FA and keeping large holdings offline.
How Cryptocurrency Enables Borderless International Payments Without Banks or Currency Conversions
Cryptocurrencies are designed to be global. Usually, you can send crypto to a Bitcoin wallet address, Ethereum address or stablecoin wallet from anywhere in the world at any time. This makes it great for international business, freelance payments, sending money to family members and international communities.
As blockchain networks are always online, international payments can be processed faster. You don’t have to wait for multiple banks to send your payment, instead it can be confirmed on a blockchain in minutes/seconds.
Multiple conversions can be avoided. For example a freelance worker based in India may be paid in stablecoins in their customers country and then converted using an exchange to Rupees. Whilst there is still a conversion in the process, it does not go through the third party banking system.
There are some practical issues stopping crypto being widely used. Governments have different rules and regulations for crypto exchanges, tax, anti-money laundering and international transactions. One must follow the law, show earnings and exchange it whenever needed.
Final Thoughts
One of the biggest benefits of cryptocurrencies for an individual using cryptocurrencies are the decentralisation, saving on costs, transparent blockchain and the ability to make borderless transfers. This is all designed to provide more freedom and inclusivity for users when using digital financial services. Crypto users must realise that crypto is a technology they have a responsibility to, and understand how it works to ensure they are following the relevant laws.